


Page 132 - CityofSouthlakeFY27Budget
P. 132
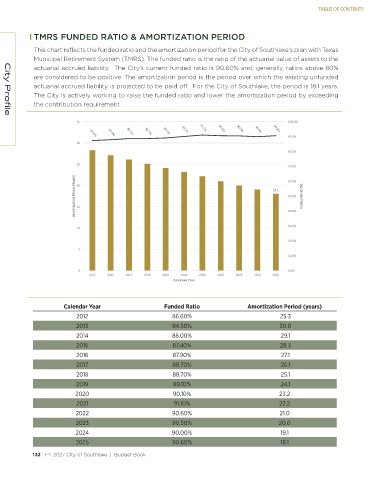
TABLE OF CONTENTS


            TMRS FUNDED RATIO & AMORTIZATION PERIOD

            This chart reflects the funded ratio and the amortization period for the City of Southlake’s plan with Texas
            Municipal Retirement System (TMRS). The funded ratio is the ratio of the actuarial value of assets to the
            actuarial accrued liability.  The City’s current funded ratio is 90.60% and, generally, ratios above 80%
            are considered to be positive. The amortization period is the period over which the existing unfunded
            actuarial accrued liability is projected to be paid off.  For the City of Southlake, the period is 18.1 years.
            The City is actively working to raise the funded ratio and lower the amortization period by exceeding
            the contribution requirement.

   City Profile
                          ϯϱ                                                                    ϭϬϬ͘Ϭй

                                                                                                ϵϬ͘Ϭй
                          ϯϬ
                                                                                                ϴϬ͘Ϭй
                          Ϯϱ
                                                                                                ϳϬ͘Ϭй
                           DKZd/ d/KE W Z/K  ;z  Z^Ϳ  ϮϬ                                  ϭϴ͘ϭ  ϲϬ͘Ϭй  &hE    Z d/K ;йͿ


                                                                                                ϱϬ͘Ϭй
                          ϭϱ
                                                                                                ϰϬ͘Ϭй

                                                                                                ϯϬ͘Ϭй
                          ϭϬ
                                                                                                ϮϬ͘Ϭй
                           ϱ
                                                                                                ϭϬ͘Ϭй

                           Ϭ                                                                    Ϭ͘Ϭй
                              ϮϬϭϱ   ϮϬϭϲ  ϮϬϭϳ  ϮϬϭϴ  ϮϬϭϵ  ϮϬϮϬ  ϮϬϮϭ  ϮϬϮϮ  ϮϬϮϯ  ϮϬϮϰ  ϮϬϮϱ
                                                            > E  Z z  Z


                      Calendar Year                    Funded Ratio                Amortization Period (years)
                          2012                            86.60%                              25.3
                          2013                            84.50%                              30.0
                          2014                            88.00%                              29.1
                          2015                            87.40%                              28.3
                          2016                            87.90%                               27.1
                          2017                            88.70%                              26.1
                          2018                            88.70%                              25.1
                          2019                            89.10%                              24.1
                          2020                            90.10%                             23.2
                          2021                             91.10%                            22.2
                          2022                            90.60%                              21.0
                          2023                            90.50%                             20.0
                          2024                            90.00%                              19.1
                          2025                            90.60%                              18.1

            132   FY 2027 City of Southlake  |  Budget Book                                                                                                                                           FY 2027 City of Southlake  |  Budget Book   133

