


Page 48 - FY 2026-2027 Adopted Budget Book
P. 48
Fund Structure


               The    financial    structure    is    defined    by    the    City’s    fund    types.    Funds    are    established    for    specific
                revenues  and expenditures related to certain activities of the City. They are further organized into various
               groups to identify their purpose.

                 Governmental Funds - used to account for all governmental-type activities. These activities consist of all
                 financial resources that cannot be categorized in other funds.

                 Proprietary  Funds  -  account  for  business  activities  where  the  cost  of  providing  services  is  financed
                 primarily through user charges. These funds operate similarly to a private business.
                    Enterprise - a separate accounting and financial reporting mechanism for municipal services for which
                    a fee is charged in exchange for goods or services. It allows a community to demonstrate to the public
                    the  portion  of  total  costs  of  a  service  that  is  recovered  through  user  charges  and  the  portion  that  is
                    subsidized by the tax levy, if any.
                    Internal  Service  -  a  separate  accounting  and  financial  reporting  mechanism  for  municipal  services
                    provided by one department to other departments on a cost-reimbursement basis.


                 Special  Revenue  Funds  -  while  a  governmental  fund  type,  the  revenue  source(s)  is  restricted  or
                 committed to a specific purpose other than capital projects or debt service. This restriction often originates
                 in state or federal law, such as the revenue from Hotel Occupancy Taxes in the Tourism Fund, which must
                 be used for tourism-related facilities and special events.

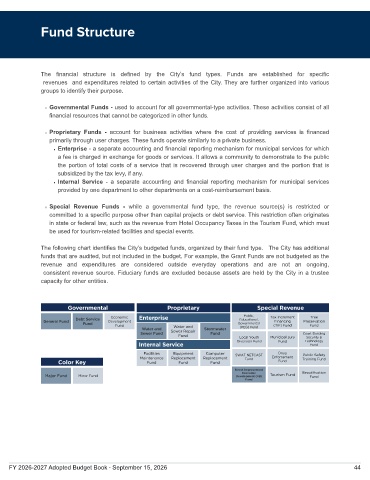
               The following chart identifies the City’s budgeted funds, organized by their fund type.   The City has additional
               funds that are audited, but not included in the budget. For example, the Grant Funds are not budgeted as the
               revenue  and  expenditures  are  considered  outside  everyday  operations  and  are  not  an  ongoing,
                consistent revenue source. Fiduciary funds are excluded because assets are held by the City in a trustee
               capacity for other entities.


    FY 2026-2027 Adopted Budget Book · September 15, 2026                                                             44

